

Cashli: Cash Advance & Rewards

- 2.79K Reviews
- 4.1
- Downloads
- 100,000+
Our take on Cashli: Cash Advance & Rewards from Appgk
When money gets tight in a shared household, the hardest part is often not finding an app but deciding who should use it, on which phone, and with what expectations. I looked at Cashli: Cash Advance & Rewards as a finance app from Cashli Funds, and my view is fairly simple: it may suit an adult who needs to investigate a small cash-advance option, but it should not be treated like a shared family wallet or a casual rewards game.
The app’s store summary presents it as a way to get up to 150 bucks when financial worries are pressing. That makes the central question less about whether the app looks convenient and more about whether its borrowing route fits your situation. I would approach it as a short-term financial tool that deserves careful reading, not as spare income and certainly not as a replacement for a household budget.
How Cashli fits into a shared household
A realistic example would be two adults sharing a phone at home, or one person using a personal phone while coordinating bills with a partner. One person may discover Cashli while looking for help with an unexpected grocery bill, transport cost, or small household purchase. The other person may reasonably want to know what is being requested, who is responsible for repayment, and whether the app is being used for a genuine emergency or for routine spending.
That distinction matters because a cash advance affects the individual account holder first. Even when the money is intended for a shared expense, the person completing the application should understand the arrangement personally rather than assuming that a partner, parent, or housemate automatically shares responsibility. I would discuss the purpose and repayment plan before using the app on a shared device.
Best Parts of Cashli: Cash Advance & Rewards
Things to Keep in Mind About Cashli: Cash Advance & Rewards
Cashli is free to install, which lowers the barrier to trying it. It does not make the financial decision risk-free. A free app can still lead to a financial commitment, and the most important information is the amount ultimately available, the repayment expectations, and any terms shown during the process. I would read every screen instead of tapping through quickly because the store summary alone is not enough to judge the full cost of an advance.
There is also a practical privacy issue with shared phones. Notifications, saved sessions, or visible activity can reveal that someone has explored a financial product. I would avoid leaving the app open, sharing login details, or handing the phone to another household member while an application is in progress. These are ordinary precautions, but they become especially important when money and personal information are involved.
News and Features Related to Cashli: Cash Advance & Rewards

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Start with the right account boundary
My first recommendation is to keep the account tied to the actual adult who is evaluating the advance. Do not create an account for a partner, older child, or housemate simply because that person is nearby, and do not assume that a shared phone should mean a shared financial profile. The cleanest arrangement is one person, one account, and one clear understanding of who is making the request.
This is particularly important in a household where several people use the same device. Before entering personal details, I would check whose email address or phone number is active, whether another person is already signed in, and whether the device is using a shared notification preview. A few minutes spent checking the account boundary can prevent confusion later.
Don't want to read the full review?
The app is rated for Everyone, but that label should not be mistaken for a recommendation that every member of a family should use a borrowing service. An age rating describes general content suitability; it does not replace an adult’s judgment about financial responsibility. In my household, I would keep any cash-advance decision with the adult whose finances and repayment plan are directly involved.
That approach also avoids a common mistake: letting a teenager explore the app because the interface appears simple. A young person might understand how to navigate a screen without understanding the consequences of borrowing. If a child uses the same phone, I would explain that finance apps are not ordinary entertainment or shopping apps and would not let them submit information on someone else’s behalf.
Screenshots
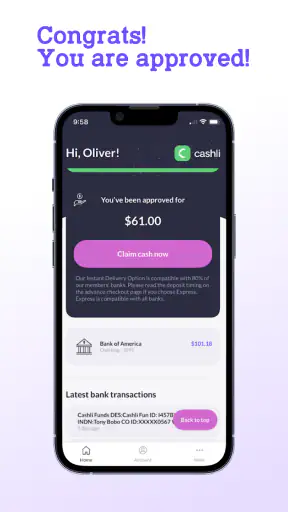
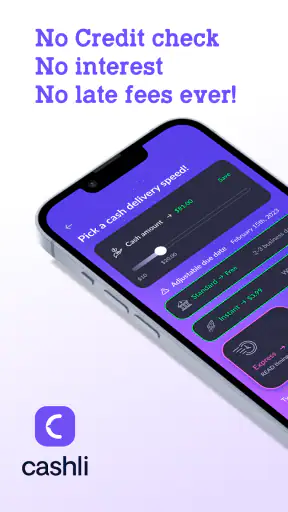
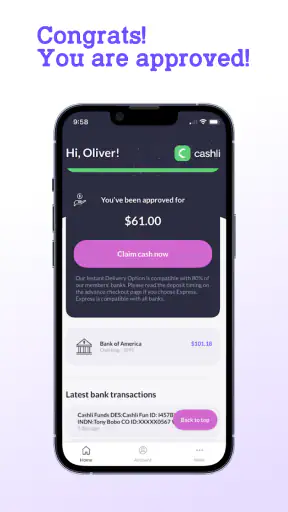
What to check before requesting money
The headline amount of up to 150 bucks is useful for setting a rough ceiling, but it should not be read as a guaranteed amount for every person. I would treat it as the maximum suggested by the store summary and wait for the in-app details to understand what might actually be available. The difference between a requested amount and a received amount can matter when a bill is due.
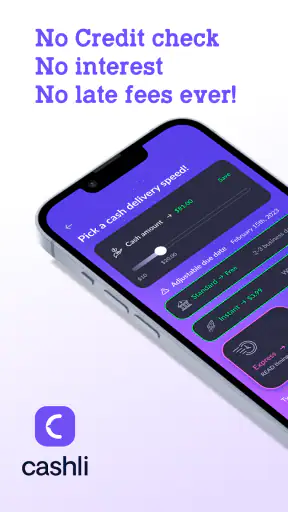
Before accepting anything, I would look for the total repayment amount, the due date, any applicable fees, and the consequences of missing the deadline. I would also check whether the money solves the immediate problem without creating a larger one a few days later. If the household has no realistic way to repay the advance from the next expected income, I would stop there and consider a different solution.
This is one of the app’s main trade-offs. Its appeal is speed and convenience for a small short-term need, while its weakness is that convenience can encourage an impulsive decision. Traditional alternatives may feel slower, but speaking with a bank, credit union, employer, or trusted financial counselor can provide a clearer view of the wider budget. For a recurring shortage, a cash-advance app is usually addressing the symptom rather than the cause.
I would also separate the “cash advance” idea from the “rewards” wording in the app’s name. Rewards can sound like a bonus layer, but they should not influence a borrowing decision. I would first decide whether the advance itself is affordable, then examine any rewards activity separately. Never borrow money merely to chase a reward or to make the app feel worthwhile.
Coordinating with a partner without blurring responsibility
For couples or housemates, coordination works best when it happens outside the account rather than through shared credentials. One person can review the household need with the other, agree on the amount, and record the expected repayment date in a private budget note. The account holder should still be the person who reads and accepts the terms.
A useful routine is to name the expense before opening the app: “This is for the electricity gap,” “This is for groceries until payday,” or “This is for an urgent repair.” If the purpose cannot be stated clearly, that is a warning sign that the request may be driven by general financial stress rather than a defined short-term need. I find this simple test more useful than relying on the app’s reassuring presentation.
Afterward, I would note the amount received and the date repayment is expected. I would not rely only on memory or on a notification appearing at the right time. If the phone is shared, reminders should be stored somewhere the responsible adult can reliably see them without exposing sensitive account information to everyone else in the home.
Households should also agree on what happens if repayment becomes difficult. That conversation is uncomfortable, but it is better than discovering the problem after the due date. If one person is borrowing for a shared bill, both adults should understand whether the household budget can absorb repayment. If the advance is personal, the other person should not be surprised by a later shortage in rent, food, or utilities.
Trust, privacy, and the age question
Cashli has an Everyone content rating, and that makes the app broadly suitable from a content perspective. I would still separate content rating from financial suitability. Money apps can involve sensitive identity and income information, so the right user is an informed adult who understands why the information is being requested and what decision they are making.
On a family tablet or shared Android phone, I would use a separate device profile when available, lock the screen, and avoid saving sensitive details in places other household members can open. I am not claiming that Cashli provides family controls; rather, these are device-level habits I would use because the app concerns personal finance. A shared device should never become an excuse for shared access to one person’s financial account.
The same principle applies to helping an older relative. It is reasonable to sit beside someone while they read the screens, but I would let that person enter their own personal information and make their own decision. Assistance should mean explaining unfamiliar wording, not choosing the amount or accepting terms for them. This protects both the user and the helper from later disputes.
I would be especially cautious if a household member has difficulty reading financial conditions, is under pressure from another person, or is already using several borrowing services. In those situations, a direct conversation with a qualified financial adviser or a trusted nonprofit service may be more appropriate than opening another app. Cashli can be convenient, but convenience is not the same as guidance.
Everyday strengths and points of friction
One genuine strength is focus. Cashli is positioned around a small, immediate cash need rather than a broad investment dashboard or a complicated long-term planning system. Someone who already understands their budget may appreciate having a straightforward place to explore an advance and related rewards. The free entry point also makes it easy to evaluate the experience before deciding whether it is relevant.
Its limitations are just as important. A small advance may cover one gap but can become another deduction from the next pay cycle. The app cannot fix irregular income, high recurring bills, or a household that is already borrowing to cover previous borrowing. It is also a poor fit for someone who wants detailed budgeting, bill negotiation, savings automation, or investment analysis. Those needs are better served by dedicated tools or human support.
I would not install it simply because the name includes rewards. A rewards-oriented feature can be useful only if it fits naturally into the user’s finances and does not distract from repayment. The right workflow is to assess the cash need, inspect the terms, and then decide whether any rewards element has practical value. Reversing that order encourages spending or borrowing for the wrong reason.
The app has attracted over 100 thousand installs, with an average rating of 4.1 from roughly 4.9 thousand ratings and about 2.8 thousand written reviews. Those figures suggest that many people have tried it and that the overall response is positive but not flawless. I read that as a reason to test the experience carefully for your own circumstances, not as proof that it will suit every household.
Who should use it, and who should choose something else?
I think Cashli is most appropriate for an adult facing a clearly defined, short-lived cash gap who can explain exactly how repayment will fit into the next budget. It may also suit someone who wants to explore a small advance without paying an installation fee and is willing to review the in-app conditions patiently. In that narrow situation, the app can be a practical option to investigate.
I would skip it if the requested money is for an ongoing expense, discretionary shopping, gambling, or another advance. I would also avoid it if repayment depends on uncertain income or if the household cannot agree on who is responsible. Someone seeking a full financial plan should use a budgeting service, bank support, or professional advice instead of expecting this app to provide broader help.
Compared with a traditional bank or credit union, Cashli may feel more accessible for a modest, urgent need, while the traditional route may offer a more established relationship and broader financial context. Compared with a budgeting app, Cashli is aimed at accessing money rather than organizing the money you already have. Compared with asking a trusted person for help, it may feel less awkward, but it still requires a careful look at obligations and repayment.
That comparison helped me place the app correctly: it is not a universal answer to financial stress. It is a specific tool for exploring a small advance, with rewards attached to the product identity, and it should be judged by the terms presented to the individual user. If the household needs stability rather than a temporary bridge, a spending review and a longer-term plan are likely to deliver more value.
My household verdict
Cashli: Cash Advance & Rewards is a free finance app developed by Cashli Funds. It was released on July 18, 2023, and the current version is 1.0.19 for devices running Android 8.0 or later. Those practical details make it easy to consider on a compatible phone, but compatibility is only the first step in deciding whether it belongs in your financial routine.
My recommendation is cautious rather than dismissive. I would use it only from the responsible adult’s own account, on a device with sensible privacy protections, and for a specific short-term need that already has a repayment plan. I would involve a partner in the household discussion without sharing credentials or assuming joint responsibility automatically.
The most important rule is to evaluate the repayment obligation before the convenience of receiving money. If the numbers work and the need is genuinely temporary, Cashli may be worth exploring. If the app would merely postpone a recurring problem, I would choose budgeting help, creditor communication, or personal advice instead.
For a shared household, that boundary is the difference between using a financial tool thoughtfully and letting a quick solution create confusion. I see Cashli as potentially useful in a narrow situation, but not as a family finance hub, a child-friendly activity, or a substitute for a sustainable household plan.
Cashli: Cash Advance & Rewards FAQ
What is Cashli: Cash Advance & Rewards, and how does it work?
Cashli: Cash Advance & Rewards is a financial app that may help eligible users access a cash advance while also offering rewards or savings-related features. After creating an account, you generally provide personal and financial information so the service can assess eligibility. Available amounts, fees, repayment terms, and reward options can vary, so review the in-app agreement carefully before accepting any offer.
Is Cashli: Cash Advance & Rewards a loan, and what fees should I expect?
A cash advance is not free money; it is typically an amount that must be repaid under the terms shown in the app. Depending on your eligibility and location, Cashli may display service charges, subscription costs, expedited-transfer fees, or other expenses. Before confirming, check the total repayment amount, due date, recurring charges, and any applicable annual percentage rate or disclosure.
Who can use Cashli, and what information is required to apply?
Eligibility may depend on factors such as age, residency, employment or income information, an active bank account, and other requirements established by Cashli or its lending partners. The app may request identity, contact, banking, and financial details for verification. Requirements and availability can differ by state or country, so downloading the app does not guarantee approval or access to an advance.
How and when do I receive the cash advance, and how is repayment handled?
If approved, Cashli should show the delivery method and estimated timing before you accept the advance. Standard transfers may take longer, while faster delivery could involve an additional fee. Repayment is commonly collected automatically from a linked bank account on the scheduled date. Make sure sufficient funds are available, and review how extensions, failed payments, or late repayments are handled.
Is Cashli: Cash Advance & Rewards safe to use?
Before using Cashli, review its privacy policy, security information, app permissions, and the identity of any lending or financial partners involved. Avoid sharing login codes or banking credentials outside the official app, and download only from a trusted store listing. Also read recent user feedback and customer-support details, since financial apps handle sensitive data and terms may change over time.











